

You already know the accepted wisdom: new cars are too expensive, and so there is an Affordability Crisis. Depending on your politics, the crisis is said to generate multiple negative effects (and the list goes beyond these):
It’s hurting industry profits (OEMs, dealers, lenders, et al.) because fewer new cars are being sold. (My rebuttal: would you rather sell 90 cars at $2,000 profit each, or 100 at $1,000?)
It’s pricing young people out of the new car market, forcing them to buy used cars, and somehow that means they will never buy new cars in the future, and that would indeed be a disaster for the industry. (My rebuttal: prove it. I’ve bought “used” houses all my life, and recently bought a “new” one, somehow overcoming my programming.)
It’s forcing lower-income people out of the (new) market, putting their car-dependent livelihoods at risk. (My rebuttal: I don’t think this demographic has been in the market for new cars for decades, if ever. Experian shows 76% of new car buyers in 2008 had Prime or Super Prime credit ratings; in 2025 it was 73%. With about 300 million cars on American roads, there are used-car choices galore. But yes, for many of our fellow Americans, the burden of car payments is heavy. I especially feel very strong empathy for people whose daily bread depends on their old clunker not breaking down. So I do support, financially, worthy organizations such as Vehicles for Change.)
It’s forcing new-car buyers to stretch their budgets ever further (see constant reminders about ultra-long loan terms; see complaints about monthly payments often cresting $1,000), setting us up for a 2008-style credit collapse and possibly a recession or worse.
Let’s take one brief look/chart at #4 today. Two caveats first:
I am not a finance expert. I thought APR meant Alabama Public Radio, that RV was recreational vehicle, and LTV was Ling-Temco-Vought. So I will refer to smarter people than I, in this case Alix Partners, specifically their latest Global Automotive Outlook.
I do believe there is an affordability challenge, for sure. Would all concerned (OEMs, dealers, lenders, consumers) prefer a wider choice of cheaper cars? Absolutely! Would it be a good idea to offer same? Yup. Should we start preparing to do so before incredibly inexpensive Chinese cars start showing up on our shores? Definitely. But these are challenges we need to address, not crises threatening extinction. A matter of semantics I guess, but words do mean things.
So just one chart re #4: are we really pushing American households to the brink, with blinged-up Range Rovers and pickups so large they have their own zip codes1? Well, in the Outlook deck Alix Partners showed a chart calculating the historic trend of new-car monthly payments in the USA as a percentage of average disposable income. Sounds like an affordability metric to me. As I do not have clearance to share the chart here, I will not; but because it used public data, I have decided to recreate it myself. Okay, with the help of Claude AI, turned up to 11 - we’re talkin’ Fable here, people. And I also asked Claude to show its work, in case you want to dig in. Here is the chart, in all its glory (Edward Tufte would kill me for this…):
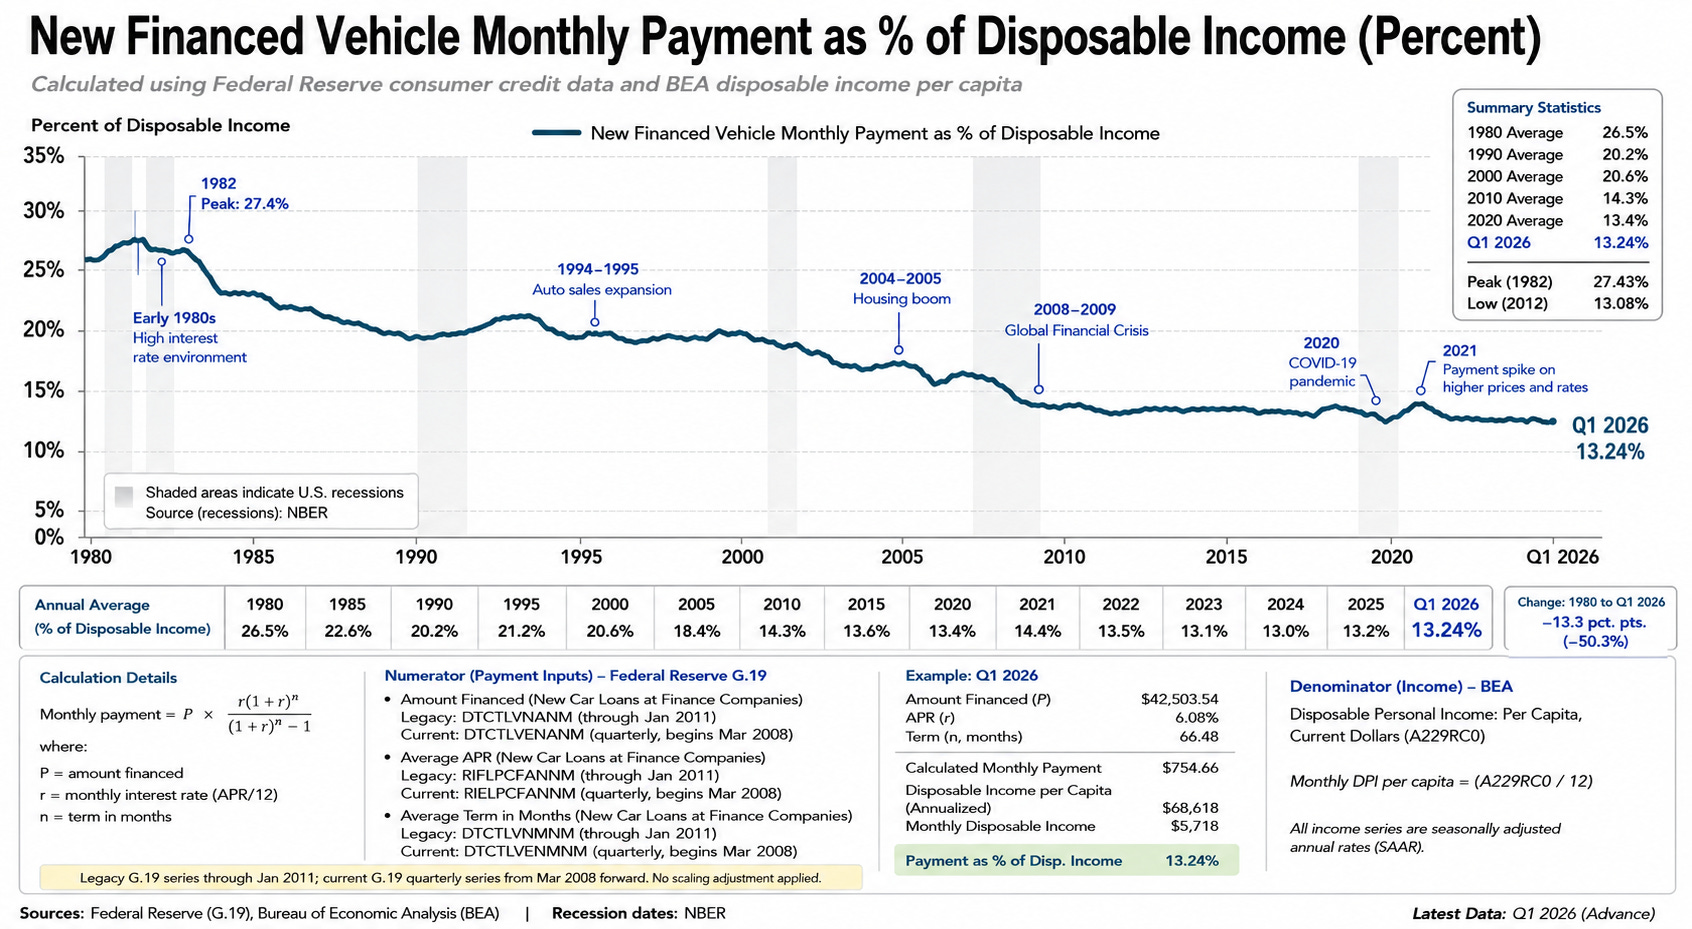
The line speaks for itself. It has gone steadily down, or stayed flat, not gone up. No crisis visible here folks, move along.
One issue I will grudgingly admit to: one can drive this line down by extending loan terms (thus reducing monthly payment even as total payments grow), and indeed over the past half-century the average loan term has soared, from about 45 (my best guess) to about 65 months (+45%) . But I will argue this makes sense regardless of affordability issues: car quality has improved so much over time that average fleet age is up dramatically, from about 8 years in 1980 to about 13 now (+60%), and while length-of-first-ownership data is harder to come by, my best estimate is that it was under 4 years in 1980 and over 6 now (+50%). So if the asset lasts longer and you keep it longer, why wouldn’t your loan term keep pace? But see caveat #1 above: let me know if this logic is flawed.
I do realize there are MANY ways to calculate affordability, so other metrics may tell a different story. And I do realize averages conceal inequalities: it would be theoretically possible (sort of) for this trend line to exist if only one person bought a car in Q1 2026, because every other American was priced out. So, stats and economics nerds out there (and I know you are out there: believe it or not my readership contains relatively few Insta fashion influencers), tell me why I am wrong. But if you do - show me your data. It’s only fair, and I will share it with my millions thousands hundreds of readers.
Sorry, I forget myself. For our younger readers, “zip codes” were numbers printed on folded paper containers called “envelopes,” within which were “letters,” sort of printouts of emails. These would be hand-delivered to your house by a federal employee, who was hired based on his or her ability to talk on a phone headset for an entire 8-hour shift. It’s kind of how DoorDash works now, but with words. Essentially, we swapped home word delivery for home food delivery. 🤔